Car Written Off in Alberta and the Payout Is Too Low? How to Dispute It
The adjuster calls with the news: your car is a total loss. Then comes the number, and it feels like a punch. It is thousands less than what similar cars are listed for in Edmonton, and nowhere near enough to replace what you had. Many Albertans assume they have to take it. You do not. Alberta has a formal process for disputing the value of a written-off car, and knowing how it works can put real money back in your pocket.
This guide explains how a car written off in Alberta is valued, how to push back on a low payout, and what happens to the wreck afterward.
How Insurers Value a Written-Off Car
When a vehicle is written off in Alberta, the insurer pays its Actual Cash Value, or ACV. That is not what you paid for the car, and it is not the cost of a brand-new replacement. It is meant to reflect what your specific car was worth just before the loss, based on its year, make, model, kilometres, options and condition.
Your deductible comes off the top. Alberta's Insurance Act allows an insurer, after a total loss, to subtract the policy deductible from the ACV it pays and then take title to the salvage. In other words, once you are paid, the damaged car normally belongs to the insurer.
Why the first offer is often low
- Valuation tools may compare your car with vehicles that have fewer options or a lower trim.
- Comparable cars may come from other markets instead of Edmonton and area.
- Recent upgrades, like new tires, brakes or a rebuilt transmission, are often missed.
- Condition may be rated lower than it really was.
Step 1: Ask for the Valuation Report
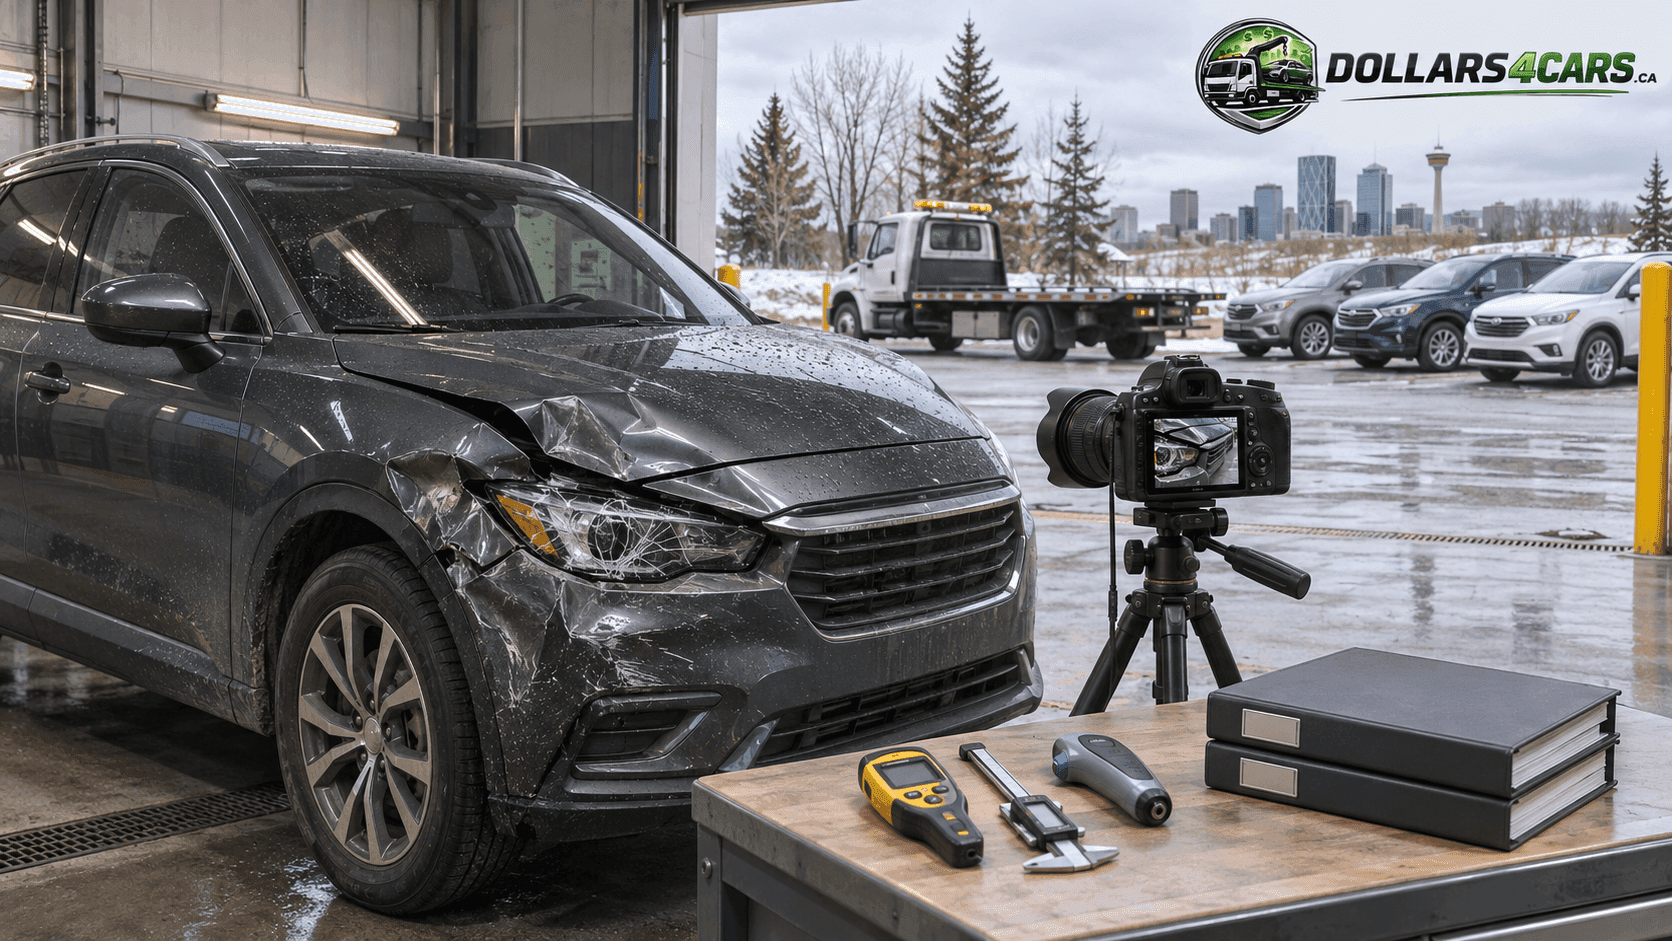
Before you argue, see how the number was built. Ask the adjuster for the full valuation report, including the comparable vehicles used, mileage adjustments and condition ratings. Check every detail: trim level, engine, drivetrain, packages and kilometres. A single wrong trim code can shift the value by thousands.
Step 2: Build Your Own Evidence
You can counter the offer by showing local listings for identical vehicles in Alberta, and receipts for recent major mechanical work or upgrades. Build a short, organized file:
- Three to five comparable listings from Edmonton and area, same year, trim and similar kilometres. Save screenshots with dates.
- Receipts for tires, brakes, major repairs, remote starter or block heater work done in the last year or two.
- Photos taken before the loss that show the car's condition.
- Maintenance records showing the car was well cared for.
- A short written summary of the value you believe is fair and why.
Send it to the adjuster in writing and ask for a written response. Many disputes end here, with an adjusted offer.
Step 3: Use Alberta's Formal Dispute Resolution Process
If you still cannot agree, Alberta law gives you a structured option. When you and your own insurer disagree about the value of insured property, the issue must be settled through the Dispute Resolution Process set out in section 519 of the Insurance Act. Your insurer must send you a copy of section 519 within 10 days of determining that there is a dispute about the amount of the loss.
To start the process, you file a proof of loss form with the insurer and make a written request to begin dispute resolution. Your adjuster can give you the proof of loss form. In general terms, each side appoints an appraiser, and if they cannot agree, an umpire decides. Ask your insurer or a lawyer about the costs involved before you begin.
Every insurer in Alberta is also required to have an ombudsperson, which is another route if you feel your claim has been handled unfairly.
| Option | Best for | Effort |
|---|---|---|
| Accept the first offer | When it already matches local market prices | None |
| Negotiate with evidence | When the offer is clearly off but the gap is modest | Low to moderate |
| Insurer's ombudsperson | When you believe the claim was handled unfairly | Moderate |
| Section 519 dispute resolution | When the gap is large and you have solid evidence | Higher, with possible costs |
Can You Keep a Written-Off Car?
Sometimes. Some insurers will let you keep the car and reduce your payout by its salvage value. That can make sense if the damage is mostly cosmetic and you can repair it cheaply. But be careful: a written-off vehicle may be branded, and a salvage brand means it must pass an inspection before it can be registered for the road again. A non-repairable brand means parts and scrap only. Branding also affects future insurance, financing and resale value.
If hail was the cause, our guide to repairing, claiming or selling a hail-damaged car in Alberta covers the specific options for hail write-offs.
Common Mistakes That Cost Money
- Accepting on the phone. Ask for the offer and valuation in writing first.
- Leaving the car in a paid storage lot. Storage fees can pile up while you negotiate, so ask the adjuster how storage is being handled.
- Forgetting personal items and plates. Remove belongings and your licence plate before the car goes to salvage. Our guide on cancelling your vehicle registration in Alberta explains what to do with the plate and any refund.
- Not checking your loan. If the car is financed, the payout goes to the lender first, and you may owe the difference.
When the Car Is Yours to Sell
If you decide to keep the salvage, or the car was never claimed through insurance, you can sell it as-is. Private buyers rarely want a heavily damaged or branded car, but a junk car buyer will value it on its parts, catalytic converter and metal. Dollars4Cars buys damaged, written-off and salvage-branded vehicles across Edmonton with free towing. Get a quick number on our cash for cars Edmonton page so you know what the salvage is really worth before you decide whether to keep it.
Frequently Asked Questions
Can I dispute an insurance total loss offer in Alberta?
Yes. Start by asking for the valuation report and sending written evidence of the car's true value. If you still disagree with your own insurer about the value, Alberta's Insurance Act requires the dispute to be settled through the section 519 Dispute Resolution Process.
How is Actual Cash Value calculated?
ACV reflects what your specific vehicle was worth just before the loss, based on its year, make, model, trim, kilometres, options and condition. It is not the original purchase price or the cost of a new vehicle.
Who owns the car after a total loss payout in Alberta?
Normally the insurer. Alberta law allows the insurer to deduct your deductible from the Actual Cash Value it pays and take title to the salvage. Some insurers let you keep the car for a reduced payout.
How long do I have to start the dispute process?
Timelines depend on your policy and the Insurance Act, so act quickly. Your insurer must send you a copy of section 519 within 10 days of determining there is a dispute. Ask your adjuster or a lawyer about your specific deadlines.